Explore

Our Services

Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua.

Web Development

Lorem ipsum dolor sit amet, consectetur adipisicing elit, sed do etc.

Database Analysis

Lorem ipsum dolor sit amet, consectetur adipisicing elit, sed do etc.

Server Security

Lorem ipsum dolor sit amet, consectetur adipisicing elit, sed do etc.

image
image
image
image
Explore

Design & Development

Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua.

image

DO YOU HAVE ANY PROJECT ?

Let’s Talk About Business Soluations With Us

image
image
image
image
image
image
image
image
image
9 ways to make your money work for you

1. Keep money in an account with the potential to earn higher interest or returns

You might as well stash your money under a mattress if you’re not holding it in a high-yield savings account, investing it through a brokerage account, or having it in another account that could come with higher earnings. Sure, keeping your money in cash gives you more control over it, but it reduces the chances of it growing. High-yield savings accounts, for instance, offer more interest on what you put in than a traditional savings or checking account would. Cash management accounts, which could offer many of the same benefits as a checking account, such as mobile check deposit and ATM debits, also tend to offer competitive rates. And over time, returns from investing in the stock market tend to be higher than what you could earn in a traditional savings or checking account. Still, past performance doesn’t guarantee future results, and you could lose money in the stock market.

2. Give money enough time in the market

You can’t expect your investments to grow exponentially overnight. In fact, you might not see any growth from day to day, particularly with lower-risk investments. A whole lot of nothing happening in the short term might tempt you to cash out.

But over the long term, you might benefit from compounding, or when earnings on your money also earn money. That’s why it’s about time in the market, not timing the market to predict when it’s best to sell or buy: The longer you’re invested, the longer compounding has a chance to do its thing.

Cashing out early is a possible growth stunter for another reason. Not only does it limit the time your money has to potentially grow, but some investment accounts and types of investments—such as 401(k)s and certificates of deposit (CDs)—could come with fees and/or tax penaltiesOpens in a new window for withdrawing money too soon.

3. Don’t give in to volatility

When you invest and the market goes up, your portfolio might follow. If the market goes down, your portfolio might be down too, and it could make you want to pull your money out. But heading for the exits too early could hinder long-term growth.

Bear in mind Wall Street history: Bull markets, when the market is going up, tend to last longer (median 42 months) than bear markets (median 19 months), which is when a market index falls by at least 20% from recent highs.1 Historically, stocks have expanded more often than contracted, and during those upswings, markets rose an average of 15% per year. They’ve even grown 1% per year during recessions.2

While volatility can be unsettling, being uninvested could be worse for your wealth. Some research has shown that missing just 5 good days in the market between 1980 and 2022 could have reduced portfolio returns by as much as 38%.3

4. Don’t let taxes cut into profits

Your investment strategy could impact your taxes. For example, if you buy a stock through a taxable brokerage account and then sell it, profits from that sale are taxable capital gains. How much you’ll pay on those gains depends on factors like how long you’ve held the stock and what tax bracket you fall in. But there’s a strategy called tax-loss harvesting which allows you to sell investments that are down, replace them with reasonably similar investments, and then offset realized investment gains with those losses. The end result is that less of your money goes to taxes and more may stay invested and working for you.

There’s also something called asset location investing, which takes into account where you hold investments (as in, the account type), as well as what you’re holding. Certain accounts, including health savings accounts (HSAs) and Roth IRAs, allow certain tax-free withdrawals; and you’re exempt from paying federal taxes for selling certain investments. (Municipal bonds are generally federally tax exempt.)

5. Intentionally set aside money for investing

If you don’t purposefully save money, then you’re likely to have less of it to invest that could potentially grow. Budgeting could help, especially if you build investing into your plan. Since there’s less of a chance you’ll spend money you don’t see, consider signing up for your employer’s retirement plan or HSA, and automating savings into those accounts, aka redirecting funds from your paycheck or perhaps a checking account to an investing or savings account.

6. Rebalance or diversify your portfolio

Let’s say you planned for your portfolio to have X% in stocks and Y% in bonds. Then as the market rose and fell, your portfolio got out of whack, making you over-index in one of those asset types. There are 2 ways to get things back on track and help limit risk: Rebalancing is when you buy and sell holdings to change the ratio of how much you have in stocks, bonds, and cash to align with your goals. Diversification is another tactic. It’s when you keep a mix of investments that don’t usually move in the same direction. That way, when some investments drop, other parts of your portfolio might rise. Not making these changes as your portfolio changes could cause your money growth to slow.

7. Look at total comp packages before accepting a new job

Salary, title, and responsibilities might command most of your attention when evaluating a job offer, but don’t neglect a new role’s total compensation package. That would include your employer’s contributions to health and disability insurance costs, and whether the company offers a retirement plan, HSA, tuition assistance, student loan repayment assistance, and employer matches to any accounts. These offerings could help you save more money more quickly, and some could even spare you some taxes. Other possible offerings, like equity, restricted stock units (RSUs), and stock grants, are a way to get into investing without having to front your own cash to do it.

8. Calculate the cost of leaving a job

Some companies require you to be vested, or at the job for a certain amount of time, before you get to keep, say, the employer match to a retirement plan or stock options granted as part of your compensation package. Make sure you run the numbers to see if leaving is worth it before you give up anything, or check if your new company is willing to pay those out as an incentive for you to join.

9. Never abandon accounts

Americans forfeit $1.5 trillion in retirement savings a year when switching jobs, according to Portability Services Network.4 Whether you have a 401(k), IRA, or other investment account, explore your options when you leave a job. And if you haven’t done so in the past, search for unclaimed funds you may have inadvertently left behind. According to the National Association of Unclaimed Property Administrators, Americans got back more than $5 billion in forgotten money from bank accounts, insurance payments, refunds, safety deposit box contents, CDs, paychecks, and security deposits in a single year.5
SEVEN TIPS FOR USING YOUR HEALTH INSURANCE EFFECTIVELY

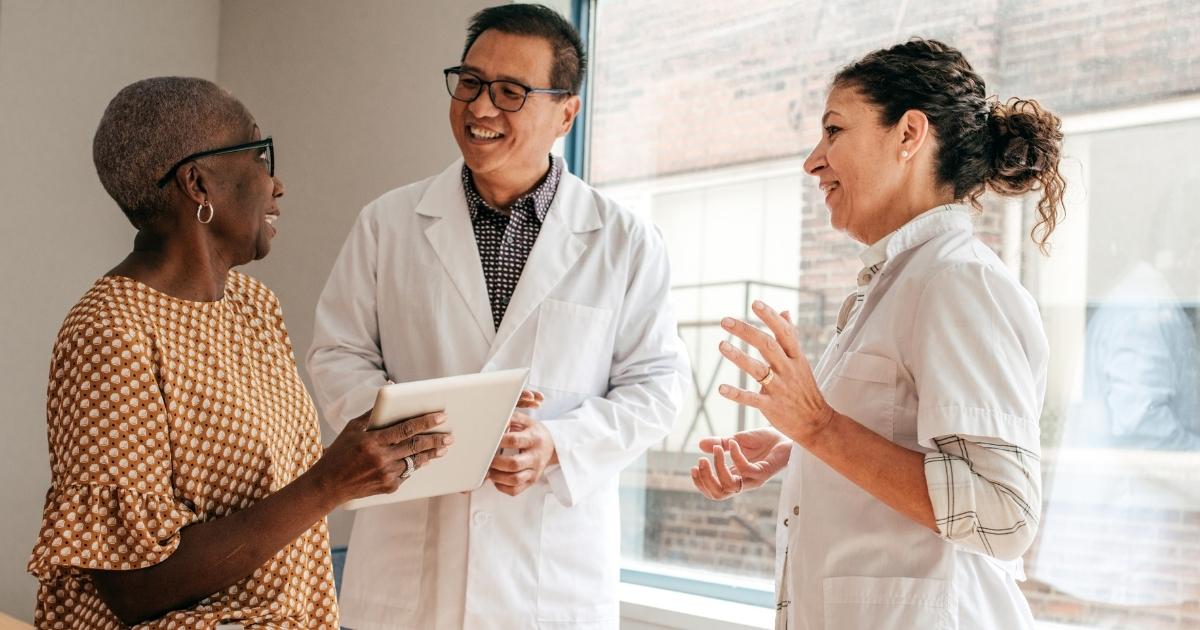
A woman speaking with two doctors.

For many people, January starts their health insurance coverage year. Now that you have it, how do you use it to keep you and your family healthy and minimize financial surprises? This article will provide you with suggestions to effectively use your health insurance.

  1. Review Your Evidence of Coverage – The Evidence of Coverage is that thick document you might get that provides the details of your plan, from the definition of terms to the costs to the rules you need to follow to have health services covered. For some, it might be a URL provided on the back of your insurance card. Either way, you receive the information, be sure to review it, especially around topics such as your network, what health services might need pre-approval, the health services covered. You are looking for any information about services you may not have used before, changes in costs and information that might be new. Sometimes, plans change just a little bit from year to year, even if it is a plan you’ve had in the past. It’s important that you keep up to date.

  2. Carry Your Health Insurance Card at All Times – You never know what might happen or when you might need health care services. Insurance cards have information that a health care provider needs to provide service and the co-payment or co-insurance amounts that could be charged. The card also has contact information in case you have questions.

  3. Use Preventive Services to Stay Healthy – Most health insurance plans offer preventative services; some offer them at low or no cost to encourage individuals to go to the doctor for their annual physicals, well-child visits, annual gynecological care, and in some cases, dental cleanings. We know that people who take advantage of these preventive services help you avoid certain diseases and catch others in their early stages, to limit the harm they can cause.

  4. Choose In-network Doctors and Health Care Services – Most health care insurance companies have a network of doctors and health care services with whom there is a contract. When you use providers from the network, it costs less money. If you have an HMO or EPO type of health care plan and use out-of-network health care services (unless in an emergency), you will have to pay the full cost; health insurance will not cover any of the costs. So, it is important to choose doctors and healthcare services in your health insurance network. Check their website or use the number on the back of your health insurance card to verify if your providers are in the network.

  5. Track Health Care Related Expenses – Use your Explanation of Benefits document mailed to you or visit your information online to track your use of health care services and your costs. You’ll want to do this to make sure information and costs are correct and also to be able to plan for your out-of-pocket costs.

  6. Plan for Health Care Costs – Health insurance is designed to share health care costs with you. Depending on the plan, that may be more or less money. It’s important to understand your plan, what it doesn’t cover, and estimate those costs. Use the Estimating Your Health Care Costs publication to help you determine how much you need to set aside to cover out-of-pocket costs.

  7. Use Tools to Solve Problems  – Sometimes things go wrong. Use information from the health insurance company website or the Evidence of Coverage booklet to find information about resolving any issues regarding billing or health care services.
WHAT IS AN FMO AND HOW CAN IT HELP MEDICARE AGENTS?

what is an fmo?


WHAT IS AN FMO AND HOW CAN IT HELP MEDICARE AGENTS?

What is an FMO? FMO, IMO, NMO … you may have heard these terms bandied about between your fellow insurance agents without knowing what they meant. There are so many acronyms, who can keep track?

In this case, all three describe organizations with very similar purposes. Specifically, an FMO is a Field Marketing Organization, while an IMO is an Independent Marketing Organization, and an NMO is a National Marketing Organization. So what do these organizations do? Well, the concept is simple. They market, sell and distribute insurance products for agents like you.

What is an FMO?

A Field Marketing Organization (FMO) is an organization that handles the marketing side of your business.

You know your goal. It’s to find the right Medicare policy for your clients and help them sign up. That means you want to focus your energy on growing your business. When you work with an FMO that handles Medicare policies, they can help you reach your business goals more effectively and efficiently.

Here’s a breakdown of how working with an FMO will improve your business.

#1. Provides support to you and your business

Every small business owner needs help. The product and sales consultants that work for the FMO will help you conduct market research and determine what Medicare products your clients need most. But that’s not all. Their staff can speed up your contracting process, handle commission audits and deal with licensing issues. All while you focus on selling!

An FMO is simply a great support team for your agency. When you hire an FMO, they come with specialized training for you, market-tested methods for growing your business, and even help with your most challenging cases.

#2. Offers the plans your clients want

To stay competitive in the Medicare insurance industry, you have to offer the plans your clients want. The agents and brokers with an FMO have access to the best national—and regional—health plan and insurer options. This means when you work with an FMO, you greatly increase your ability to find the right Medicare insurance plans for your senior clients.

With an FMO’s specialized and name brand carriers, you’re suddenly a whole lot more competitive!

#3. Gives you access to quoting and enrollment tools

FMOs provide you with access to advanced marketing tools. Most FMOs let you use their free CMS-approved quoting tool, so you can easily compare and contrast the prices of different types of Medicare plans for your clients. With this quote optimization, you’ll address the client’s specific and changing insurance plan needs with fewer roadblocks and challenges.

In addition, within those tools, some FMOs give you access to supplemental policies your clients might want or need.

#4. Doesn’t affect your commissions

In case you’re concerned about your commission, don’t be. There will be no reduction to your commission when you use an FMO. An FMO usually receives an override from the insurance companies they contract with to support the lead generation, advanced technology and training they provide to independent agents. Of course, this override payment from the insurance company is completely separate from your commission.

And, don’t forget, FMOs can experience chargebacks—just like you!

#5. Allows for your independence

You chose to become an independent agent, so you know you value your freedom. Don’t think that working with an FMO means giving up your agency (no pun intended!). But do your research, and find an FMO that has an Open Release Policy. Yes, you still have to sign contracts with most FMOs. But the Open Release Policy allows you to collaborate with an FMO—no strings attached.

So, what is an FMO? FMOs are here to support you. As a team of marketing consultants, FMOs provide the tools you need to achieve your mission as a Medicare agent. Contact us today for more information. Get that marketing burden off your shoulders!

image
image
image
image
image
image
image
image