9 ways to make your money work for you

1. Keep money in an account with the potential to earn higher interest or returns

You might as well stash your money under a mattress if you’re not holding it in a high-yield savings account, investing it through a brokerage account, or having it in another account that could come with higher earnings. Sure, keeping your money in cash gives you more control over it, but it reduces the chances of it growing. High-yield savings accounts, for instance, offer more interest on what you put in than a traditional savings or checking account would. Cash management accounts, which could offer many of the same benefits as a checking account, such as mobile check deposit and ATM debits, also tend to offer competitive rates. And over time, returns from investing in the stock market tend to be higher than what you could earn in a traditional savings or checking account. Still, past performance doesn’t guarantee future results, and you could lose money in the stock market.

2. Give money enough time in the market

You can’t expect your investments to grow exponentially overnight. In fact, you might not see any growth from day to day, particularly with lower-risk investments. A whole lot of nothing happening in the short term might tempt you to cash out.

But over the long term, you might benefit from compounding, or when earnings on your money also earn money. That’s why it’s about time in the market, not timing the market to predict when it’s best to sell or buy: The longer you’re invested, the longer compounding has a chance to do its thing.

Cashing out early is a possible growth stunter for another reason. Not only does it limit the time your money has to potentially grow, but some investment accounts and types of investments—such as 401(k)s and certificates of deposit (CDs)—could come with fees and/or tax penaltiesOpens in a new window for withdrawing money too soon.

3. Don’t give in to volatility

When you invest and the market goes up, your portfolio might follow. If the market goes down, your portfolio might be down too, and it could make you want to pull your money out. But heading for the exits too early could hinder long-term growth.

Bear in mind Wall Street history: Bull markets, when the market is going up, tend to last longer (median 42 months) than bear markets (median 19 months), which is when a market index falls by at least 20% from recent highs.1 Historically, stocks have expanded more often than contracted, and during those upswings, markets rose an average of 15% per year. They’ve even grown 1% per year during recessions.2

While volatility can be unsettling, being uninvested could be worse for your wealth. Some research has shown that missing just 5 good days in the market between 1980 and 2022 could have reduced portfolio returns by as much as 38%.3

4. Don’t let taxes cut into profits

Your investment strategy could impact your taxes. For example, if you buy a stock through a taxable brokerage account and then sell it, profits from that sale are taxable capital gains. How much you’ll pay on those gains depends on factors like how long you’ve held the stock and what tax bracket you fall in. But there’s a strategy called tax-loss harvesting which allows you to sell investments that are down, replace them with reasonably similar investments, and then offset realized investment gains with those losses. The end result is that less of your money goes to taxes and more may stay invested and working for you.

There’s also something called asset location investing, which takes into account where you hold investments (as in, the account type), as well as what you’re holding. Certain accounts, including health savings accounts (HSAs) and Roth IRAs, allow certain tax-free withdrawals; and you’re exempt from paying federal taxes for selling certain investments. (Municipal bonds are generally federally tax exempt.)

5. Intentionally set aside money for investing

If you don’t purposefully save money, then you’re likely to have less of it to invest that could potentially grow. Budgeting could help, especially if you build investing into your plan. Since there’s less of a chance you’ll spend money you don’t see, consider signing up for your employer’s retirement plan or HSA, and automating savings into those accounts, aka redirecting funds from your paycheck or perhaps a checking account to an investing or savings account.

6. Rebalance or diversify your portfolio

Let’s say you planned for your portfolio to have X% in stocks and Y% in bonds. Then as the market rose and fell, your portfolio got out of whack, making you over-index in one of those asset types. There are 2 ways to get things back on track and help limit risk: Rebalancing is when you buy and sell holdings to change the ratio of how much you have in stocks, bonds, and cash to align with your goals. Diversification is another tactic. It’s when you keep a mix of investments that don’t usually move in the same direction. That way, when some investments drop, other parts of your portfolio might rise. Not making these changes as your portfolio changes could cause your money growth to slow.

7. Look at total comp packages before accepting a new job

Salary, title, and responsibilities might command most of your attention when evaluating a job offer, but don’t neglect a new role’s total compensation package. That would include your employer’s contributions to health and disability insurance costs, and whether the company offers a retirement plan, HSA, tuition assistance, student loan repayment assistance, and employer matches to any accounts. These offerings could help you save more money more quickly, and some could even spare you some taxes. Other possible offerings, like equity, restricted stock units (RSUs), and stock grants, are a way to get into investing without having to front your own cash to do it.

8. Calculate the cost of leaving a job

Some companies require you to be vested, or at the job for a certain amount of time, before you get to keep, say, the employer match to a retirement plan or stock options granted as part of your compensation package. Make sure you run the numbers to see if leaving is worth it before you give up anything, or check if your new company is willing to pay those out as an incentive for you to join.

9. Never abandon accounts

Americans forfeit $1.5 trillion in retirement savings a year when switching jobs, according to Portability Services Network.4 Whether you have a 401(k), IRA, or other investment account, explore your options when you leave a job. And if you haven’t done so in the past, search for unclaimed funds you may have inadvertently left behind. According to the National Association of Unclaimed Property Administrators, Americans got back more than $5 billion in forgotten money from bank accounts, insurance payments, refunds, safety deposit box contents, CDs, paychecks, and security deposits in a single year.5
SEVEN TIPS FOR USING YOUR HEALTH INSURANCE EFFECTIVELY

A woman speaking with two doctors.

For many people, January starts their health insurance coverage year. Now that you have it, how do you use it to keep you and your family healthy and minimize financial surprises? This article will provide you with suggestions to effectively use your health insurance.

  1. Review Your Evidence of Coverage – The Evidence of Coverage is that thick document you might get that provides the details of your plan, from the definition of terms to the costs to the rules you need to follow to have health services covered. For some, it might be a URL provided on the back of your insurance card. Either way, you receive the information, be sure to review it, especially around topics such as your network, what health services might need pre-approval, the health services covered. You are looking for any information about services you may not have used before, changes in costs and information that might be new. Sometimes, plans change just a little bit from year to year, even if it is a plan you’ve had in the past. It’s important that you keep up to date.

  2. Carry Your Health Insurance Card at All Times – You never know what might happen or when you might need health care services. Insurance cards have information that a health care provider needs to provide service and the co-payment or co-insurance amounts that could be charged. The card also has contact information in case you have questions.

  3. Use Preventive Services to Stay Healthy – Most health insurance plans offer preventative services; some offer them at low or no cost to encourage individuals to go to the doctor for their annual physicals, well-child visits, annual gynecological care, and in some cases, dental cleanings. We know that people who take advantage of these preventive services help you avoid certain diseases and catch others in their early stages, to limit the harm they can cause.

  4. Choose In-network Doctors and Health Care Services – Most health care insurance companies have a network of doctors and health care services with whom there is a contract. When you use providers from the network, it costs less money. If you have an HMO or EPO type of health care plan and use out-of-network health care services (unless in an emergency), you will have to pay the full cost; health insurance will not cover any of the costs. So, it is important to choose doctors and healthcare services in your health insurance network. Check their website or use the number on the back of your health insurance card to verify if your providers are in the network.

  5. Track Health Care Related Expenses – Use your Explanation of Benefits document mailed to you or visit your information online to track your use of health care services and your costs. You’ll want to do this to make sure information and costs are correct and also to be able to plan for your out-of-pocket costs.

  6. Plan for Health Care Costs – Health insurance is designed to share health care costs with you. Depending on the plan, that may be more or less money. It’s important to understand your plan, what it doesn’t cover, and estimate those costs. Use the Estimating Your Health Care Costs publication to help you determine how much you need to set aside to cover out-of-pocket costs.

  7. Use Tools to Solve Problems  – Sometimes things go wrong. Use information from the health insurance company website or the Evidence of Coverage booklet to find information about resolving any issues regarding billing or health care services.
WHAT IS AN FMO AND HOW CAN IT HELP MEDICARE AGENTS?

what is an fmo?


WHAT IS AN FMO AND HOW CAN IT HELP MEDICARE AGENTS?

What is an FMO? FMO, IMO, NMO … you may have heard these terms bandied about between your fellow insurance agents without knowing what they meant. There are so many acronyms, who can keep track?

In this case, all three describe organizations with very similar purposes. Specifically, an FMO is a Field Marketing Organization, while an IMO is an Independent Marketing Organization, and an NMO is a National Marketing Organization. So what do these organizations do? Well, the concept is simple. They market, sell and distribute insurance products for agents like you.

What is an FMO?

A Field Marketing Organization (FMO) is an organization that handles the marketing side of your business.

You know your goal. It’s to find the right Medicare policy for your clients and help them sign up. That means you want to focus your energy on growing your business. When you work with an FMO that handles Medicare policies, they can help you reach your business goals more effectively and efficiently.

Here’s a breakdown of how working with an FMO will improve your business.

#1. Provides support to you and your business

Every small business owner needs help. The product and sales consultants that work for the FMO will help you conduct market research and determine what Medicare products your clients need most. But that’s not all. Their staff can speed up your contracting process, handle commission audits and deal with licensing issues. All while you focus on selling!

An FMO is simply a great support team for your agency. When you hire an FMO, they come with specialized training for you, market-tested methods for growing your business, and even help with your most challenging cases.

#2. Offers the plans your clients want

To stay competitive in the Medicare insurance industry, you have to offer the plans your clients want. The agents and brokers with an FMO have access to the best national—and regional—health plan and insurer options. This means when you work with an FMO, you greatly increase your ability to find the right Medicare insurance plans for your senior clients.

With an FMO’s specialized and name brand carriers, you’re suddenly a whole lot more competitive!

#3. Gives you access to quoting and enrollment tools

FMOs provide you with access to advanced marketing tools. Most FMOs let you use their free CMS-approved quoting tool, so you can easily compare and contrast the prices of different types of Medicare plans for your clients. With this quote optimization, you’ll address the client’s specific and changing insurance plan needs with fewer roadblocks and challenges.

In addition, within those tools, some FMOs give you access to supplemental policies your clients might want or need.

#4. Doesn’t affect your commissions

In case you’re concerned about your commission, don’t be. There will be no reduction to your commission when you use an FMO. An FMO usually receives an override from the insurance companies they contract with to support the lead generation, advanced technology and training they provide to independent agents. Of course, this override payment from the insurance company is completely separate from your commission.

And, don’t forget, FMOs can experience chargebacks—just like you!

#5. Allows for your independence

You chose to become an independent agent, so you know you value your freedom. Don’t think that working with an FMO means giving up your agency (no pun intended!). But do your research, and find an FMO that has an Open Release Policy. Yes, you still have to sign contracts with most FMOs. But the Open Release Policy allows you to collaborate with an FMO—no strings attached.

So, what is an FMO? FMOs are here to support you. As a team of marketing consultants, FMOs provide the tools you need to achieve your mission as a Medicare agent. Contact us today for more information. Get that marketing burden off your shoulders!

What is an FMO is in the Health Insurance World

Deep Dive Into FMO for Health Insurance

The health insurance industry is complex and ever-changing, driven by evolving regulations, diverse consumer needs, and technological advancements. Within this labyrinthine landscape, Field Marketing Organizations (FMOs) serve as crucial intermediaries, bridging the gap between health insurance carriers and independent insurance agents. This article aims to provide an in-depth understanding of what an FMO is in the health insurance world, including its functions, benefits, and relevance to agents and brokers.

What is an FMO in Health Insurance?

Field Marketing Organizations, colloquially known as FMOs, occupy a unique and indispensable niche within the sprawling tapestry of the health insurance industry. While their function as intermediaries between insurance carriers and agents is often highlighted, this barely touches upon the multifaceted roles these organizations play. On the surface, one could sum up an FMO’s role as a conduit through which agents access an array of insurance products. Yet, a closer look reveals a more intricate model designed to bolster both the efficiency and effectiveness of independent insurance agents.

A Versatile Portfolio

At the cornerstone of an FMO’s offerings is a versatile product portfolio. This isn’t merely a collection of insurance policies but an intricately curated selection of products that span various carriers, each with their own set of features, advantages, and even limitations. By aligning with an FMO, agents can effectively become one-stop shops for their clients, capable of addressing a spectrum of health insurance needs, whether that’s for individuals, families, or specialized groups like senior citizens. This portfolio diversification enables agents to position themselves as trusted advisors, rather than just salespeople.

Beyond Sales: Training and Skill Development

While the product portfolio offers an immediate tangible benefit, FMOs bring long-term value through comprehensive training and skill development programs. These aren’t cookie-cutter seminars but targeted training modules that dive into the complexities of health insurance products, market trends, and selling techniques. With the health insurance landscape being subject to frequent policy changes and regulatory updates, staying informed is crucial. FMOs typically employ industry experts who craft training materials and offer insights, keeping agents up-to-date and poised to offer expert advice to clients.


Marketing and Branding Support

In today’s digitally connected world, effective marketing transcends traditional boundaries. FMOs often have dedicated marketing teams that help agents establish their brand. This can range from providing customizable marketing materials, like brochures and digital content, to even more complex services such as SEO optimization and social media strategy. Essentially, they offer agents the tools to not just reach their audience but to do so with impactful, high-quality content that converts leads into clients.

Administrative Powerhouse

One of the more underappreciated aspects of what an FMO offers lies in its administrative capabilities. Agents often find themselves bogged down with the minutiae of paperwork, compliance, and client management—a daunting workload that leaves little room for actual selling. FMOs often come equipped with robust Customer Relationship Management (CRM) systems, streamlined paperwork processes, and even dedicated support for contractual and compliance issues. These services liberate agents from administrative drudgery, allowing them to focus on client interaction, product understanding, and ultimately, sales.

The Financial Edge

Lastly, it’s essential to talk about the financial benefits, which are often the most immediate draw for many agents. FMOs often negotiate higher commission rates with carriers due to the sheer volume of business they generate. Agents affiliated with FMOs often find themselves benefiting from these higher commissions, which can make a significant difference in their overall earnings. Some FMOs even offer bonus structures for high-performing agents, adding another layer of financial incentive.

In sum, defining what an FMO is in the health insurance world requires more than a cursory glance at its basic functions. It is a multi-dimensional entity designed to uplift the capabilities of independent insurance agents in an increasingly competitive and complex landscape. From product diversification to skill enhancement, marketing acumen to administrative efficiency, and financial benefits to long-term career growth—FMOs offer a comprehensive suite of advantages that empower agents to excel.

How Jane Found Success Through an FMO

Jane was a diligent insurance agent who found herself stuck in a rut. Despite her best efforts, she was unable to grow her client base or even offer a variety of products that could meet diverse client needs. She had relationships with a couple of health insurance carriers but felt severely limited by the lack of options. It was then that she stumbled upon an FMO that promised extensive support in all aspects of her career.

Within a few months of partnering with the FMO, Jane’s career took a turn for the better. She underwent comprehensive training programs that polished her sales skills and enhanced her product knowledge. She no longer had to fret about administrative bottlenecks; the FMO took care of those. Perhaps most impressively, her product portfolio expanded exponentially. With a wider array of products, she could cater to a more diverse client base, from young adults to senior citizens. The FMO even provided her with marketing tools and strategies that significantly boosted her outreach. Today, Jane is a successful insurance agent with a thriving client base, all thanks to her decision to work with an FMO.


For example, take the case of Smith Insurance Agency, a small-scale, independent firm that faced stagnation for several years. After partnering with a reputable FMO, the agency saw a 30% growth in its customer base within just one year. The FMO not only provided a broad spectrum of insurance products for the agency to offer but also supported its sales funnel with targeted lead-generation strategies. This real-world example highlights the tangible benefits that can accrue from an FMO partnership.

FMOs and Technology: A Harmonious Partnership

In the era of digital transformation, FMOs have not been left behind. Many modern FMOs offer sophisticated technology solutions, from comprehensive Customer Relationship Management (CRM) systems to analytics dashboards that help agents track and assess their performance metrics. These tools are not just add-ons; they are integral parts of how FMOs add value to an agent’s practice.

For instance, advanced CRM systems can streamline client management, allowing agents to focus on what they do best—advising clients and selling policies. Some FMOs even offer mobile applications that facilitate on-the-go client management and policy tracking, a much-needed feature in today’s fast-paced world. Through technology, FMOs help agents keep pace with industry changes and customer expectations, offering a digital edge that is increasingly becoming indispensable.


Regulatory Landscape: Navigating the Maze with FMOs—An In-Depth Analysis

In an industry steeped in regulations, keeping track of legislative changes is not just a necessity but a full-time job in itself. Health insurance is one of the most regulated sectors in the United States. It falls under the ambit of multiple laws at both federal and state levels, including landmark legislation like the Affordable Care Act (ACA). Navigating these regulations becomes a Herculean task for insurance agents who already have to juggle between client consultations, policy explanations, and sales efforts. This is where Field Marketing Organizations (FMOs) bring unparalleled value in the form of regulatory assistance, enabling agents to concentrate on their core functions without compromising compliance.

Making Sense of Legislation

Interpreting laws related to health insurance is not a straightforward task. Regulations often contain technical jargon that requires specialized legal training to fully comprehend. FMOs bridge this gap by employing experts familiar with both the health insurance industry and its related laws. These experts dissect complex legislations into easily digestible information, cutting through the legalese to provide agents with summaries, guides, or bullet-point lists that help them understand the laws that affect their business. This service proves invaluable in helping agents comprehend how changes in legislation could impact various insurance products, premiums, or claims procedures.

Proactive Updates and Training Modules

Federal and state laws related to health insurance are not static; they evolve in response to socio-political factors and public health needs. The legislative landscape can thus shift quickly, sometimes within the span of a few months. FMOs actively monitor these changes and provide proactive updates to agents, often via newsletters, webinars, or specialized training sessions. This real-time information keeps agents ahead of the curve, equipping them with the latest regulatory knowledge to confidently guide their clients through purchasing decisions.


Legal Consultations and Compliance Checks

Another layer of regulatory support that FMOs offer comes in the form of legal consultations and compliance checks. Let’s say there’s a new rule affecting the enrollment process for Medicare Advantage plans. An FMO could organize a workshop, featuring legal experts who can elucidate the rule’s implications and guide agents through the changes needed in their operational procedures. Furthermore, many FMOs offer periodic compliance checks, which could involve auditing an agent’s practices to ensure they meet all state and federal requirements. These audits can serve as a preventive measure, helping agents rectify potential compliance issues before they become legal headaches.

The Future: Adapting to Consumer-Centric Regulations

The trend in health insurance regulation is moving inexorably toward a more consumer-centric model. This entails more transparent disclosure requirements, stronger patient protections, and more stringent oversight on policy pricing. Understanding these consumer-centric regulations is not just important for compliance but also crucial for building trust with clients. FMOs, recognizing the shift in regulatory focus, provide tools and resources aimed at simplifying these consumer-centric policies, ensuring agents can adapt their selling techniques to align with this evolving paradigm.


Challenges and Considerations: What to Keep in Mind

While FMOs offer a multitude of benefits, they are not without challenges. One of the most cited concerns is the potential for reduced independence. Because FMOs often require exclusivity or quasi-exclusivity agreements, some agents feel they are giving up some freedom to conduct business on their terms. It’s important to weigh this against the benefits to determine if it’s the right choice for your specific situation.

Moreover, always scrutinize the terms of your engagement with an FMO. Some may offer a seemingly fantastic suite of services but might recoup their costs through reduced commissions or fees. Always read the fine print and, if possible, consult with peers or mentors who have experience working with FMOs.

By delving into case studies, technology trends, and regulatory considerations, one can appreciate the complex but immensely beneficial role that FMOs play in the health insurance world. From amplifying sales to ensuring compliance, FMOs serve as multifaceted partners for insurance agents looking to elevate their careers and better serve their clients. The dynamics of what an FMO is in the health insurance world extend far beyond basic services; they encapsulate a wide range of support mechanisms designed to facilitate success in an ever-evolving industry.

How Do FMOs Get Paid?

NH-How-Do-FMOs-Get-Paid

I know what you’re thinking. Are you seriously publishing this for all the world to see? The subject of money is always touchy.

How an FMO gets paid – or how any of us gets paid – is just one of those things that’s not talked about.

But, as you can tell, we’re going there. From who pays who to chargebacks, you’re going to learn more about how FMOs get paid than you probably care to know.

What is an FMO?

An FMO is a Field Marketing Organization. Some companies also call it an IMO, or Independent Marketing Organization, but it’s still the same thing. It’s really just whatever a company wants to call it.

NMO, or National Marketing Organization, is also the same thing, but it just lets people know you have a national footprint versus a regional footprint.

Years ago, there wasn’t a market for an FMO because the insurance companies took care of it with captive agents. However, staff members require health insurance, a 401 (k), a salary, travel expenses… it gets expensive, and the insurance companies were looking for a way to get away from that model.

The reason FMOs exist is because most insurance companies got away from captive agents. (That’s also why most insurance companies are led by lawyers and actuaries.) They were looking for ways to get more distribution, so they went to people like us who had built a strong agency and said, “Why not build a marketing company?”

So that’s how New Horizons came to be, and that’s how most other FMOs came to be.

John-and-Jeff

John Hockaday and Jeff Sams

How FMOs/IMOs Make Their Money

An FMO deals in volume.

An insurance company goes to an FMO and asks them to market their product. To be an FMO, you have to promise them however many millions worth of business. In exchange, that insurance company gives you a contract that’s high enough to make an override.

It’s not uncommon for an FMO to have a number they have to hit – say $4 million in production.

Does the Override Come Out of the Agent’s Commission?

The override the FMO gets doesn’t come out of what the agent gets. The insurance company pays the agent and the insurance company pays the FMO.

Is the Override Different on Different Products?

Yes, the override does fluctuate from product to product. Life products and ancillary products have a much higher override than a Medicare Supplement.

Do FMOs Get Charged Back Just Like Agents Do?

Absolutely.

The FMO is also responsible if the agent does something illegal. For example, if the agent takes an advance and never places the policies, they can run off with the advance. Guess who has to pay that back? The FMO. That’s actually happening to us right now.

That’s also why most FMOs don’t feel great about giving advances unless you’re a proven, trusted producer.

John-and-Roger

John Hockaday and Roger Bland

Why Does an FMO Deserve an Override Anyway?

An IMO or FMO ought to have a staff in place to help with contracting, accounting, and in today’s world, digital marketing. That’s what separates a true IMO from a general agency.

If they’re going to have a website, a quote engine, etc., that costs us money to produce and to keep it up and going.

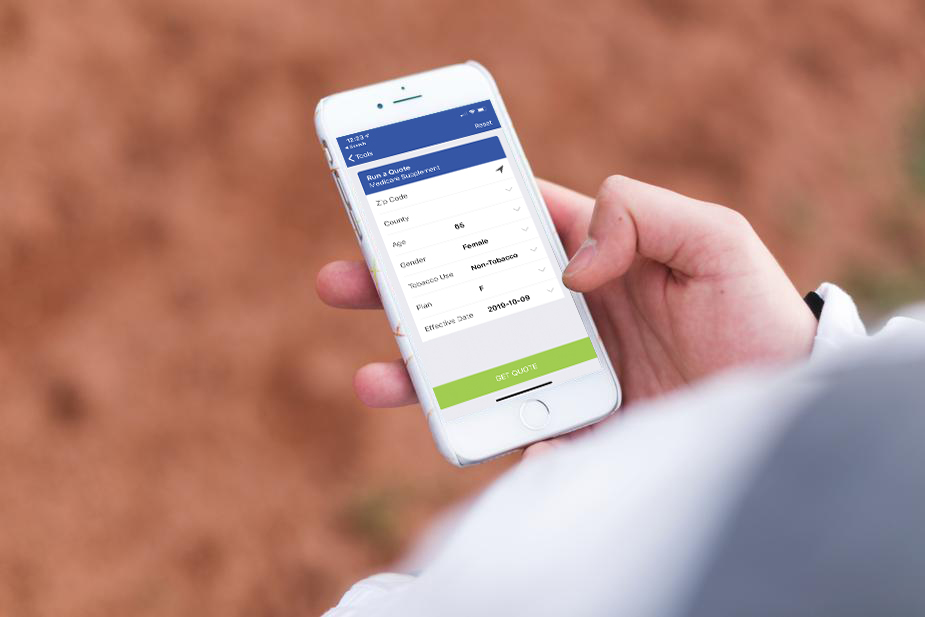
NH-quote-engine-on-phone

The New Horizons quote engine mobile app in action.

FMOs help with leads sometimes, so lead costs, marketing campaigns, Christmas bonuses, etc.

You also have out-of-state license fees, and for every carrier, you have to pay that. For some states, if you don’t think you’re going to write much there, it isn’t worth it.

If I’m an agent out here writing, I’m asking questions like:

  • Does the FMO give you contests to win where you can win additional cash?
  • Does the FMO have trips you can win that are coming from the FMO?
  • Do they offer training?

All those things.

If an FMO is doing all that, they deserve an override. If they do nothing, I’m not sure they do.

One of our latest initiatives is Medicare Advantage, so if you’re looking for a great Medicare Advantage FMO, we’d love to earn your business.

We offer free MedicareCENTER access, Medicare Advantage Sales Training, and tons of back-office support.

Read more: 4 Reasons to Sell Medicare Advantage With New Horizons Insurance Marketing

Why Not Become an FMO to Get the Highest Commission?

It’s no secret that a great personal producer can put a lot of money in his pocket. However, new agents can sometimes be a bit naive in their thinking.

It’s not uncommon for a new agent to say something like, “I’m going to write $30,000 in production, so I want the top contract!”

It just doesn’t work that way. To have the top contract, we’re talking in the millions.

Many personal producers are lucky to do $200,000. Most produce less than $50,000. To have a number of $3 or $5 million – that’s why an FMO can get a top contract.

It Takes Money to Grow

Quite honestly, most people don’t want to make the investment to get to that next level, which is an IMO or FMO. It’s going to cost you money to get there. An agent has to decide – am I going to get out of personal production and get into management?

A personal producer also doesn’t have to worry about all the other things you do when it comes to running an organization. However, the idea is if you can get big enough, you can make numbers you can never make on your own.

You gotta go big or go home. You can’t be a small IMO.

I remember when John and I were an MGA (Managing General Agency), and we wrote about $400,000 per year. They said, “Listen, just keep going and hiring and it won’t be long until you’ll be writing $3-4 million per year.”

I thought there was no way, but it turned out they were right.

It takes a while, and now we’re right around $20 million in Medicare Supplement production.

It’s been a good, gradual growth, and that’s thanks to all of the hard-working, motivated agents we have out in the field. If you’re reading this, thank you for helping us grow, and we sincerely value your friendship.

The Benefits of Joining a Top Insurance FMO

If you’re wondering what exactly an FMO is and why you should join one, you’ve come to the right place! We have the answers you’ve been looking for to help you determine if you should join an FMO and how you can benefit from doing so!

What Is an Insurance FMO?

A field marketing organization (FMO) is a company that acts as a liaison between agents and carriers, connecting the two through a contract. The best FMOs provide additional services to agents through excellent and individualized support and state-of-the-art resources and tools.

How Does Joining an FMO Help Me as an Insurance Agent?

Contracts

Most FMOs will offer a mix of contracts from big-name carriers with a national presence and small-name carriers with a regional presence. Some only specialize in certain areas or products, like Medicare or life insurance, while others provide a more diverse portfolio of options.

More Than Medicare

Of course, we can’t speak on behalf of all Medicare FMOs, but here at Ritter, we are more than Medicare. Beyond offering a vast array of health and life products, we have knowledgeable and energetic support staff ready to help you through every step of the sales process.

Ritter partners with many preferred life and health insurance carriers, so the plans your clients want will likely be accessible. Our sales specialists know your target market and will inform you about the best carriers to partner with or new and competitive products that you could benefit from selling. They can also help you with topics like trainings, certifications, and completing enrollments. Support with ordering marketing and sales supplies and assistance with commission inquiries are also benefits available to you!

Online Contracting Assistance

At the most basic level, FMOs provide contracts for their agents. The number of contracts one can offer depends on its size and resources. Not only do they provide contracts, but they should also be able to provide contracting assistance. Completing contracting for any carrier can be confusing. You have to find the paperwork, fill it out correctly, and know where to send it.

Quote Quickly and Accurately

Ritter has a number of tools for agents to use that help them reach their sales goals with ease, like the Medicare Quote Engine! This system allows you to quote multiple plans from several carriers simultaneously for faster rate generation. Its easy-to-use platform was developed with three initiatives in mind: efficiency, speed, and intelligence! And since the data on the quote engine is updated monthly, you can be confident that the information you give your clients is accurate!

Enroll Painlessly Online

Shop & Enroll is another top tool that is exclusive to Ritter! This CMS-approved, consumer-facing quote engine allows agents to collect electronic Scopes of Appointment and enroll clients directly online. There is no financial commitment to create a site, only the benefit of marketing with your own personal URL for easy lead generation. Creating your own Shop & Enroll site is quick and easy and will greatly benefit your sales process!

Stay Organized with a CRM

We’ve also launched a client relationship management (CRM) system, the Ritter Platform, which was developed exclusively for agents registered with Ritter. Revamped with our agents in mind, the Platform provides agents with more user-friendly features and easy access to the tools that improve the way they do business. Our comprehensive agent dashboard does it all, by providing insight into your clients, contracts, enrollments, downlines, and commissions, just to name a few! If it’s important to your insurance business, you can track it in the Ritter Platform. You can also try out the Drug Cost Estimator tool, which allows you to easily enter and save prescription drug lists for each client and run a quote directly from the data collected in your Shared Client Record. Use our Tasks tool to conveniently cross of to-dos and keep your day running smoothly.

WHAT IS AN FMO AND HOW CAN IT HELP MEDICARE AGENTS?

What is an FMO? FMO, IMO, NMO … you may have heard these terms bandied about between your fellow insurance agents without knowing what they meant. There are so many acronyms, who can keep track?

In this case, all three describe organizations with very similar purposes. Specifically, an FMO is a Field Marketing Organization, while an IMO is an Independent Marketing Organization, and an NMO is a National Marketing Organization. So what do these organizations do? Well, the concept is simple. They market, sell and distribute insurance products for agents like you.

What is an FMO?

A Field Marketing Organization (FMO) is an organization that handles the marketing side of your business.

You know your goal. It’s to find the right Medicare policy for your clients and help them sign up. That means you want to focus your energy on growing your business. When you work with an FMO that handles Medicare policies, they can help you reach your business goals more effectively and efficiently.

Here’s a breakdown of how working with an FMO will improve your business.

#1. Provides support to you and your business

Every small business owner needs help. The product and sales consultants that work for the FMO will help you conduct market research and determine what Medicare products your clients need most. But that’s not all. Their staff can speed up your contracting process, handle commission audits and deal with licensing issues. All while you focus on selling!

An FMO is simply a great support team for your agency. When you hire an FMO, they come with specialized training for you, market-tested methods for growing your business, and even help with your most challenging cases.

#2. Offers the plans your clients want

To stay competitive in the Medicare insurance industry, you have to offer the plans your clients want. The agents and brokers with an FMO have access to the best national—and regional—health plan and insurer options. This means when you work with an FMO, you greatly increase your ability to find the right Medicare insurance plans for your senior clients.

With an FMO’s specialized and name brand carriers, you’re suddenly a whole lot more competitive!

#3. Gives you access to quoting and enrollment tools

FMOs provide you with access to advanced marketing tools. Most FMOs let you use their free CMS-approved quoting tool, so you can easily compare and contrast the prices of different types of Medicare plans for your clients. With this quote optimization, you’ll address the client’s specific and changing insurance plan needs with fewer roadblocks and challenges.

In addition, within those tools, some FMOs give you access to supplemental policies your clients might want or need.

#4. Doesn’t affect your commissions

In case you’re concerned about your commission, don’t be. There will be no reduction to your commission when you use an FMO. An FMO usually receives an override from the insurance companies they contract with to support the lead generation, advanced technology and training they provide to independent agents. Of course, this override payment from the insurance company is completely separate from your commission.

And, don’t forget, FMOs can experience chargebacks—just like you!

#5. Allows for your independence

You chose to become an independent agent, so you know you value your freedom. Don’t think that working with an FMO means giving up your agency (no pun intended!). But do your research, and find an FMO that has an Open Release Policy. Yes, you still have to sign contracts with most FMOs. But the Open Release Policy allows you to collaborate with an FMO—no strings attached.

So, what is an FMO? FMOs are here to support you. As a team of marketing consultants, FMOs provide the tools you need to achieve your mission as a Medicare agent. Contact us today for more information. Get that marketing burden off your shoulders!

What are the Benefits of Working with an Insurance FMO

What is an Insurance FMO

A Field Marketing Organization (FMO) or an Insurance Marketing Organization (IMO) is a company that offers insurance products and services to insurance agents or agencies.

Most FMO’s will normally offer services above and beyond insurance products, but the services offered will vary by company.

We will review some of the products and services you should look for, as well as important questions to ask, before you start working with an FMO.

Like with any business, having the right support can help supercharge your success.

 Do I Need an Insurance FMO to Get Contracted Through a Carrier?                    

While there are a small handful of carriers that will contract agents directly, the vast majority of name-brand, competitive insurance carriers will require you to work through an FMO to obtain their products.

In general the ability to work directly with the carrier, if available at all, will be challenging as they prefer to contract with agents or agencies that can meet certain profitability objectives.

An FMO can offer contracts to agents that they might not be able to acquire individually. They can do this because of the volume and relationship the FMO has developed with the carriers. This puts an FMO in a unique position to have a quality selection of products to offer agents.

A good FMO will work consistently to get the best contracts with top companies, and offer them to agents and agencies of all sizes. They should be a pillar of support, helping you maximize your efforts, and allow you to focus on supercharging your business.

Benefits of Working With An Insurance FMO / IMO:

Earn Top Commissions with Additional Support

Some FMO’s will offer full, vested commissions on your sales. You would not get paid any more if you were contracted directly through the carrier, even if it were available. In addition to vested commissions, you may find additional benefits with an FMO versus going direct.

 What’s the difference between an Independent Agent & Captive Agent                      

Independent:

An Independent Agent is not an employee of another agency. They are free to contract with any company they feel is a good fit for their business. They are their own boss, they set their own hours, and choose the products they want to go to market with.

An Independent Agent has more freedom to choose how they do business and will enjoy a higher commission on his contracts.


Captive:

A Captive Agent works for a company or agency. They are required to take on the products chosen by the company they are employed with. Typically, Captive Agents earn lower commissions than Independent Agents, but receive more support.

Nevertheless, the added support and training they receive will come at the cost of lower commissions.

Regardless of whether you end up contracting as a Captive or Independent Agent, make sure to fully understand the Release Policy of the FMO you choose.

Open Release Policy                     

Some FMO’s offer an Open Release Policy, meaning:

If at any time you want to part ways with the FMO, you simply ask for a release, stop working with the company, and still retain your book of business.

There are some good FMO’s out there that will offer a straight up release policy with no strings attached. This type of relationship will allow the most flexibility with your business.

This relationship allows agents to operate like a business and not get locked into something that may not be in their best interest.

Other FMO’s offer limited release options, which may not allow an agent to be released easily, or won’t allow an agent to retain their book of business. This means that the business the agent generates while working with a company, should they decide to leave, may belong to the FMO and NOT the agent.

Note! It is essential to be clear on this point before selecting an FMO! Some FMO’s will have strings attached to a release policy that may not be in favor of the agent.

Quoting Tools for Insurance Agents

FMOs generally provide agents and brokers access to a CMS (Centers for Medicare & Medicaid Services) approved quoting tool.

This will enable you to quote Medicare Advantage Insurance Plans (Medicare Part C), Medicare Supplement Insurance Plans (Medigap Policies), and Medicare Part D Prescription Drug Plans.

Ask the FMO if their quoting tool offers full disclosure and is not filtered or hiding carriers from your view. This is important if you want to get a complete view of the market.

CRM Tools for Insurance Agents

FMOs that want to help you compete more effectively will usually offer customer relationship management (CRM) tools.

This software will help you keep track of your client from first contact through enrollment, and offer a calendar and reminder system to ensure you know what you need to do – daily, weekly, and monthly – to help you build your business.

Sell Top Tier Insurance Products

FMOs offer a range of products to help you build the perfect portfolio, ensuring you remain competitive in your market space.

A strong FMO will generally offer agents and brokers with a wide range of product options, including regional and national health plan options from brand name carriers with highly ranked plans.

Insurance Product and Marketplace Certification

Two of the most valuable benefits offered by an FMO are:

Help getting your required annual sales certification (or re-certification) from AHIP (America’s Health Insurance Plans) and Product training for your contracted carriers.

While certification for specific products will be required no matter which FMO you work with, some will offer reduced rates for required AHIP training.

A good FMO will notify you when new certifications are available each year.

Dedicated Support for Insurance Agents

Experienced support is a must for an insurance agent. A good FMO will have an experienced team with deep industry and product knowledge along with the understanding of being an agent in today’s marketplace.

Many may be or have been agents themselves. The company should assign you to a marketer that will treat you like a business owner and a partner, and have your success in mind.

A good FMO knows that they are successful only when the agents they work with are successful.


 Room for Your Insurance Business to Grow

Make sure to align yourself with an FMO that will give credit where credit is due. Ensure the company will provide a commission level that will increase as your production increases.

You work hard to grow your business, and an FMO should recognize your efforts with “upper level” contracts for you to grow into.

Final Thought

If your potential FMO offers most, or all of the above, ask if any of your associates are already doing business with them. The best reviews come from people currently working with an FMO, who can share their experience and quickly help you determine if it’s a proper fit.

It’s also a good idea to speak with a rep from the FMO to get an idea what kind of support you will receive, and to get a feel for the attitude of the employee.

Try to get an idea of the turnover rate at the company. A good FMO will usually have a core of experienced marketers that have been there for years.

Choosing an Insurance FMO is like choosing a business partner, and having support outside of the insurance carrier is important while building a block of business. It’s important to ensure the FMO will be providing the best products and services for your business.

Even a superhero needs support from time to time. A good FMO can provide that kind of support. Just make sure you do your homework and ensure they have your best interest in mind.

5 Reasons to Work with an FMO

A field marketing organization (FMO) offers many benefits to independent agents and agencies. FMOs are also commonly called IMOs (independent marketing organizations) and NMOs (national marketing organizations) and vary through the insurance industry, but all have one thing in common: they market, sell, and distribute insurance products.

But not all FMOs are created equal. They come in various shapes and sizes, offering a wide variety of products and services for independents. Yet, there are a few common denominators to look for when exploring and choosing an FMO.

Support

Having a dedicated product/sales consultant makes a big difference when it comes to doing business. Product and sales consultants help you cut out the market research and analytics of what products to offer your clients and why. Additionally, having access to support teams that provide expedited contracting, handling escalated issues such as commission audits and licensing/appointment issues truly comes in handy to keep you doing what you do best.

Marketing

FMOs generally provide free access to agents and brokers to a CMS (Centers for Medicare & Medicaid Services) approved quoting tool. This will enable you to quote Medicare Advantage Insurance Plans (Medicare Part C), Medicare Supplement Insurance Plans (Medigap Policies), and Medicare Part D Prescription Drug Plans. If you’re working with a top FMO, they may also provide additional product lines within their quoting tools and portals.

Products

FMOs offer a range of products that can be tailored for your portfolio, ensuring you remain competitive in your market space. FMOs generally offer agents and brokers with regional and national health plan and insurer options, including brand name and highly ranked plans.

Contracts

An FMO can offer contracts to agents that they might not be able to acquire individually. They can do this because of the volume and relationship the FMO has developed with the carriers. This puts an FMO in a unique position to have a quality selection of products to offer agents.

They typically make a percentage of commission on top of the full commission you make. This works great for independents because it leaves more profit in your accounts. Higher level contracts are available based on the size of your agency, number of agents, amount of revenue, etc.

Commissions

It’s important to partner with an FMO offering top or full commissions on your sales. Look for FMOs that don’t pay out commissions unless the carrier or insurer requires payment from the FMO. In most cases, carriers pay out commissions directly to the agent or broker. This means that an FMO can offer the highest commission levels from the carrier while still allowing agents to work as independently as possible.

‍

5 Considerations for Insurance Agencies When choosing an FMO

Many businesses rely on wholesalers for product distribution, and the agency side of the insurance industry is no different. Insurance wholesalers, often referred to as field marketing organizations (FMOs), provide insurance agencies access to the products they broker and offer their customers.

FMOs should serve two distinct roles: an indispensable linchpin connecting insurance agencies with the right insurance carrier products and a strategic growth partner.

Choosing the right insurance FMO can significantly impact an agency’s efficiency, competitiveness and overall client satisfaction. Here are five considerations insurance agencies should keep in mind when selecting an FMO.

1. Product Category Expertise

Different FMOs often specialize in specific areas of risk, from Medicare Advantage and Medicare Supplements to life insurance or other niches such as hospital indemnity, dental, cancer or disability.

As an insurance agency owner, it’s crucial to choose an FMO with a strong track record and in-depth knowledge in your areas of focus. They should be able to facilitate precise growth strategy execution, help capture specific market share and provide invaluable advice for more complex insurance scenarios you or your sales team may face.

2. Carrier Relationships

An FMO’s relationship with its carrier partners is another key factor to consider.

The strength and depth of these relationships can directly influence the scalability of your growth strategy by bringing unique business development opportunities and strategic partnerships. An FMO with robust, long-standing carrier relationships is more likely to help you secure key relationships that facilitate sales growth.

3. Responsiveness And Support

Just like any other business, impeccable customer service and prompt responsiveness are vital in keeping operational processes in an insurance agency running smoothly.

Timeliness in handling requests, quote turnarounds and navigating carrier negotiations can make a significant difference in client satisfaction and the overall efficiency of your operations. Hence, select an FMO that values and delivers excellent customer service, consistently communicates and promptly addresses any issues or concerns.

4. Deployable Technology

As the insurance sector continues to embrace digital transformation, the technological prowess of an FMO becomes increasingly important.

FMOs should have sophisticated technology to help streamline processes, improve data accuracy, and expedite service delivery. For example, ask the FMO whether they offer streamlined quoting, enrollment, commission processing and customer retention reporting in a consolidated system that can be accessed independently or via API through your existing agency management system.

This is a critical area to ask questions about during your selection process.

5. Compliance Capabilities

Compliance is a moving target that is consistently adapting to the changes in the insurance industry, especially given how fast technology is moving.

Insurance agencies should ensure that the FMO they choose not only adheres to the various state and federal regulations for their specific product lines but can also serve as a resource to help the agency service their customers in a compliant way.

For example, an agency may have a marketing initiative they want to use to generate new Medicare customers, and the governing entity, CMS, may require approval for all customer-facing lead generation. Ask FMOs whether they have the ability to not only provide guidance but also submit the initiative for approval and manage it to completion.

In conclusion, selecting an insurance FMO can make or break your success in the industry, so you should consider your choice carefully, whether you are adding new product lines or starting an agency from the ground up. By carefully considering an FMO’s expertise, carrier relationships, agency support, accessible tech tools and compliance expertise, insurance agencies can establish partnerships that enhance their competitive edge and contribute to their growth and success in the industry. Take your time during the selection process, and don’t be afraid to ask detailed questions.